Ryan Darani is a freelance research-motor-optimization specialist based mostly in the Uk.
Designing an Seo tactic on a small budget can be difficult, but creating site visitors is possible.
Get started by doing your analysis on the marketplace and accumulating facts, and then create your manufacturer consciousness.
Thanks for signing up!
Obtain your favorite topics in a personalised feed while you happen to be on the go.
Competing in Google’s search success can be daunting. As an Search engine marketing specialist, I have worked with a lot of startups that have modest budgets but massive aspirations, and the issue I am normally confronted with is, “How can we contend from X?”
X is typically a manufacturer with 20 many years of organic and natural Search engine optimization expansion that dominates a unique sector. They exist in virtually every field, and often, there is extra than one particular. No startup desires to go head-to-head with a firm with an Search engine marketing budget that exceeds seven figures a 12 months.
The response to beating a further company’s Search engine marketing is to discover the gaps in their strategy and be tactical with how you regain marketplace share from them.
Here are 5 simple ways to start out generating organic and natural site visitors to your web-site right away, with a minimal but very well-placed spending plan.
1. Have an understanding of your total-addressable market place
Prior to you look at Website positioning a advancement channel for your startup, you will need to build current market desire in your niche. Search traffic is pushed by billions of queries occurring each working day. Your career is to calculate particularly how lots of of these queries are related to your startup.
You should really be in a position to:
Have an understanding of competitor industry share
Determine enlargement alternatives
Set up the intent of your sector
Knowledge on these fronts will aid you fully grasp two things: in which you have to have to devote cash and wherever your most important natural and organic wins are likely to appear from.
If you happen to be in the early phases of your company, likelihood are you will never have substantially (or any) shopper information to lean on for tips. This is why, initially, we create progress tactics on key phrases.
2. Accumulate the details
Research knowledge has become much more reputable above the previous decade, and you can now lean on instruments like Ahrefs and Semrush to discover what you need.
You can leverage information details like:
Approximated search volume: working with third-occasion click on knowledge to estimate how several individuals look for for a unique time period or phrase every single thirty day period
Keyword knowledge: what precise terms and similar phrases you should be making use of to generate site visitors
Targeted visitors prospective: a rough estimate of how much targeted traffic the top natural and organic final result is producing from a keyword each thirty day period
CTR (click on through fee) curve models: an estimate of how several people today simply click a internet site in the outcomes page, which decreases as the posture gets larger
Although 3rd-occasion info has inherent restrictions, it will allow for you to quantify your market with much more conviction. Your purpose below is to use as quite a few knowledge factors as achievable to get a finish picture of your current market and the keyword phrases that formulate your natural and organic opportunity.
The challenging component is probably ending up with thousands of key terms without cleansing your info. Facts cleansing can be extensive, so below are a couple tough-and-quickly policies to enable you do this:
Group your keyword phrases into types and subcategories
Get rid of any misspellings or outdated key terms
Remove any keyword phrases that have no visitors likely
Delete any duplicates
You should really stop up with a checklist of grouped keywords and phrases that have lookup quantity and site visitors prospective. This implies you can concentrate on types that have the finest possible for targeted traffic without having wasting funds on content first.
3. Build material efficiencies and procedures
At the time you know which categories have likely, you now need to fill that gap. The only way to do this is with material.
Men and women are likely to overcomplicate material advertising and marketing, but it really is simple. Your task is to be front of thoughts through the entire client journey.
Startups generally never profit from acquiring a substantial model existence in the very first six to 12 months, relying on your field. Which indicates leading-of-funnel visitors will be how you take in non-manufacturer market share, or key phrases and lookups that really don’t have the title of your firm, and create model awareness.
Web optimization depends on developing topical authority and topical relevance, each of which aid you continue to reinforce your capacity to rank in the success webpages. Google has said it would have no motive to believe in a website with fewer than 30 web pages, because it takes advantage of information to recognize what your model is. If you proceed to generate and distribute higher-top quality written content at scale regularly, Google has far more offered information and facts to evaluate you.
The benchmark for large-good quality material is distinct for every market. But some really hard-and-rapidly rules to think about are:
Distinctive value that no other opponents present
Use of loaded media (movie, visuals, audio)
Responses the user’s query quickly and with no “fluff”
Matches the user’s intent (i.e., are they seeking to purchase or just search?)
Will not rely way too closely on disruptive adverts
Sentences are succinct and effortless-to-study
There are no set boundaries on what establishes you as an authority. This takes persistence and the belief that continuing to do the right factor for the lookup engines and your buyers will finally pay out off. Dependent on my past working experience, most websites should assume a bare minimum of six months before they see traction. At the time you start out seeing this initial uplift, the compound influence of Web optimization will come into engage in.
4. Develop your brand awareness
Google would like to rank brand names, not internet sites. Anyone can launch a site, but not all people can take the time to create a manufacturer that men and women identify and appreciate.
Reputation, various sources of site visitors, term of mouth, and affiliation to a product or assistance make a manufacturer stand out. The least difficult way to realize these is getting your model described on well-liked sites.
Startup founders tend to overcomplicate this by making an attempt to reinvent the wheel. Continue to keep it straightforward by:
Reacting to newsworthy developments and gatherings
Making insightful and distinctive info to distribute
Staying keen to share your thoughts as an specialist in your subject
There are platforms like HARO (Support A Reporter Out) and Response Source where brands can post qualified commentary, thoughts, and reports to journalists. Commonly, you’ll acquire a few e-mails a day with journalist requests if you signal up. In the early stages, I might pitch to just about every pertinent web page.
PR is not only wonderful for brand name recognition but also for hyperlink constructing. One-way links are without doubt a person of the most effective alerts Google uses to rank a internet site, but not each individual connection is created the very same.
Effective, authoritative inbound links have significantly much more excess weight than lesser-recognised internet sites. This is due to the fact Google frequently values dependable information outlets as trusted resources. Receiving a backlink from a web-site like this is deemed an incredibly potent vote of self confidence in Google’s eyes. The much more you can do this, the improved it will be for your rankings and natural website traffic.
5. Seem outdoors Google for referral site visitors
At last, don’t depend fully on Google for advancement. You can just take a solitary piece of articles and repurpose it throughout as quite a few platforms as you like.
Becoming ready to make targeted visitors from well known web-sites like Pinterest, Facebook, Reddit, and big news stores is 1 of the most impressive strategies to supercharge your Web optimization.
Google takes advantage of these indicators to validate how common your model may possibly be. This is just not noted any where in their formal guidelines, but about the earlier 10 years of position web sites, referral targeted visitors has experienced a huge effect on product sales and rankings.
For case in point, if your brand has been mentioned along with nine other brand names in an professional roundup, this hyperlink will enable you develop authority about time. The more mentions and links you obtain from other appropriate websites, the a lot more opportunity you have to make organic and natural visitors.
The up coming time you plan a piece of information, consider the time to talk to on your own: Where by can I get this featured? Where can I distribute it? What one-way links could I accomplish?
Trustworthy net entry has come to be a simple need to have for education, do the job and even well being treatment, nonetheless a lot of Transylvania County people do not have desktops in their properties or entry to the online.
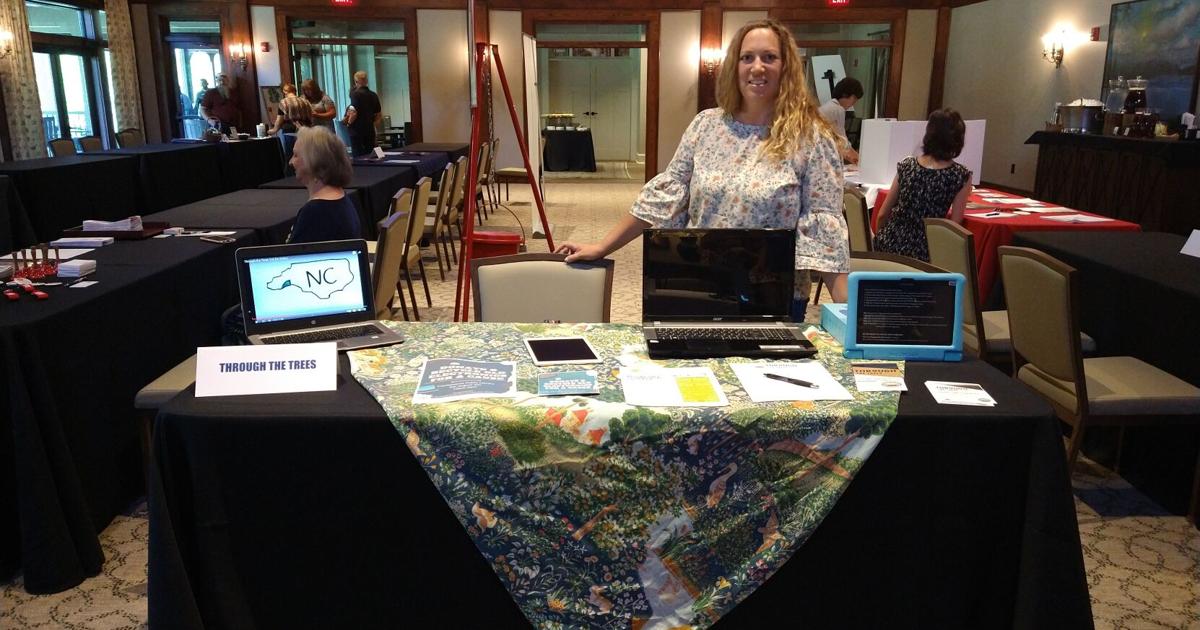
Neighborhood nonprofit Through the Trees will hold a engineering machine travel at the Transylvania County Library on Aug. 6, from 10 a.m. to 2 p.m. The group will collect utilised objects such as tablets, laptops and personal computers to refurbish them and redistribute to those in need through county.
As a result of the Trees aims to join people today as a result of engineering and not long ago been given a $30,000 Dogwood Health and fitness Have faith in grant to bridge the digital divide in Transylvania County with the aim of helping more than a thousand folks by the finish of the 12 months.
“When Dogwood Wellness Have faith in enable us know that we were chosen, we could not prevent smiling,” stated Yvette Brooks, the organization’s executive director and founder. “Their guidance is funding broadband expansion, technological know-how aid, refurbishing products and digital literacy initiatives. They are serving to us triple our influence this year and we even employed our first coordinator. With their aid, we are on our way to bridging the electronic divide listed here in Transylvania County.”
NCBroadband defines the digital divide as “the hole between those who have access to engineering, the web and digital literacy coaching, and people that do not,” defined Brooks. She mentioned virtually a quarter of Transylvania County inhabitants have no entry to the world wide web and as opposed to some other counties in the location most rural Transylvania County citizens simply cannot receive wired broadband providers at any rate and electronic subscriber traces which transmit info over telephone wires is usually the only alternative. The challenge is compounded for very low earnings residents who cannot manage to shell out for any type of world wide web assistance.
By way of the Trees advocates for rural broadband accessibility to aid very low money households use for federal grants to subsidize access expenses and it also refurbishes desktops and tablets for men and women in have to have in addition to furnishing training to established up and use technologies.
The business began its perform when pandemic shutdowns emphasized the need for trusted technologies at house.
In 2021 organizers helped a lot more than 50 families and this calendar year have already served 53 more ones.
With the assist from Dogwood Health Belief the business has been able to seek the services of its initially coordinator, Briana Mendoza, to broaden services and present bilingual support for nearby Spanish- talking families.
“I reach out to people and determine out what they require, no matter whether that is obtaining their world-wide-web back on or encouraging them utilize for subsidies to afford to pay for the web,” said Mendoza, who operates 25 several hours each individual week. “If they are in require, are their kids in require of products to get their schoolwork carried out, or just get academic applications? I am there to aid them.”
She mentioned it is extremely hard when another person are not able to communicate English to go by way of personal enterprise and government programs when making use of for internet subsidies, turning on internet at residence or just possessing world-wide-web questions.
“Even if they have it in Spanish, I’d however have to translate it simply because it is not the standard Spanish that most people are used to,” she said. “There’s a lot of slang words and phrases in Spanish, so some of these proper words that the companies use, customers really do not genuinely know what that suggests.”
Mendoza stated many households have been appreciative of the products and services and a lot of mom and dad have been primarily grateful for the academic apps downloaded on tablets all through the school 12 months and to entertain children through summer months holiday.
“Bring new life to your old units by donating them,” inspired Brooks. “We’ll refurbish the device and then distribute it to individuals in require.”
To study much more about this corporation, get hold of information on web support or how to donate, go to the web page www.throughthetrees.us or simply call (828) 351-3972.
LOS ANGELES, May 23, 2022 /PRNewswire/ — AgeMatch.com™, an age-gap dating internet site, introduced currently the start of new and updated sites for distinct age teams members’ tastes. Now, in reaction to the slogan “Elite and Attractive Dating Throughout the Age Divide”, it is user-centered with correct content serving mature and younger members.
According to the survey of 3762 top quality associates, 44{4224f0a76978c4d6828175c7edfc499fc862aa95a2f708cd5006c57745b2aaca} of customers want straightforward and quick to use features. 36{4224f0a76978c4d6828175c7edfc499fc862aa95a2f708cd5006c57745b2aaca} of people like a cellular-welcoming version. On the other hand, 71{4224f0a76978c4d6828175c7edfc499fc862aa95a2f708cd5006c57745b2aaca} of senior members want to improve the desktop web site style and attribute.
The new internet site aspect styles, articles and tools that can help boost entry for older users and highlight web site rewards. The consumer-concentrated internet site for AgeMatch delivers quick-to-adhere to explanations for accessing to unique features, these as concept, spark, report, lookup and filters.
With a person-focused landing page, AgeMatch adds diverse fresh content and apparent assistance to improve accessibility.
For the first element, AgeMatch instantly qualified prospects associates to produce an account with electronic mail. No individual data is expected.
For the second part, only age range preference is demanded. Set significantly less information, shell out far more attentions to individual profiles.
Actual-time reviews from actual members are linked on the homepage. It is shown to members and potential customers to examine others’ achievements tales and check out the true user working experience.
AgeMatch also attaches fantastic value to preserving consumer privateness. A new data verification perform that will allow customers to assessment manually as well as by way of equipment aid. It will not entry a user’s individual facts with no permission. With the new AI verification operate, all associates will be filtered instantly. If users know that their possible dates have been vetted, they’re considerably less possible to waste their time on anyone who isn’t really worthy of their time.
A comprehensive crew of AgeMatch staff members delivered 24/7 shopper services and manually critique profiles to verify their identification. It is devoted to shelling out notice to see every customer as an person to deliver significant high-quality service.
“Our vital shopper targets are experienced males and eye-catching women of all ages. The new design and style ought to truly feel aspirational, trendy and practical. The use of modern and approachable typefaces fulfills all-age groups’ will need. Consumers need to usually be the very first. We have a mission for providing the greatest for extended-expression & very best passions of consumers.” Mentioned Jennifer Kelly, the products supervisor of AgeMatch.
About AgeMatch™
Launched in 2001, AgeMatch is the qualified age hole courting web page for productive experienced adult men hunting for interesting girls. It is dedicated to gratifying consumers of various ages and supporting them find associates more effectively.
For extra information and facts, make sure you go to AgeMatch.com. iOS application and Android application is also available on application retailer.
Europe as it is today has been forged in times of crisis. The European Union (EU) was created in response to the ravages of World War II. The fall of the Berlin Wall marked the start of a period of economic catching up by economies in Central and Eastern Europe. The 2008 financial crisis and the eurozone crisis that followed led to more financial cooperation among European countries. The COVID-19 pandemic then triggered a higher level of fiscal coordination through the NextGeneration EU fund.
Most recently, the Russian invasion of Ukraine not only is a humanitarian catastrophe but has exposed a range of fragilities, from food security and energy to defense. The war has accentuated the reality that resilience depends on a strong economy with strategic autonomy in these critical areas that has long been taken for granted.
Technology is pivotal, too. Unless Europe catches up with other major regions on key technologies, it will be vulnerable across all sectors on growth and competitiveness—compromising the region’s relatively robust record on sustainability and inclusion—as well as security and strategic strength, hindering long-term resilience. Given seismic events within its own continent, a robust Europe is arguably needed more than ever. Yet to make that a reality will require the region to address a slow-motion competitiveness crisis that has quietly been unfolding for two decades, centered on its corporate and technology gap with other major regions. That is the topic of this article. Confronting this gap will require leaders to show the same resolve and collaboration as they initially displayed in their response to the war in Ukraine.
Although Europe has many high-performing companies, in aggregate European companies underperform relative to those in other major regions: they are growing more slowly, creating lower returns, and investing less in R&D than their US counterparts. This largely reflects the fact that Europe missed the boat on the last technology revolution, lagging behind on value and growth in information and communications technology (ICT) and on other disruptive innovations.
ICT and other tech sectors have spawned a range of transversal technologies, which are spreading horizontally across sectors and determining competitive dynamics. This research looks at ten transversal technologies and finds that Europe leads on only two of the ten. If Europe is not successful in competing in these technologies, it could also lose its strongholds in traditional industries. To give just one example, Europe has been a leader in automotive but could become a laggard in autonomous driving.
The stakes are high. We estimate that corporate value added of €2 trillion to €4 trillion a year could be at stake by 2040—value that could generate wages, employment, investment, and economic growth to the broader benefit of society. To put the estimated value at stake into perspective, that would be equivalent to 30 to 70 percent of Europe’s forecast GDP growth between 2019 and 2040, or one percentage point of growth a year; six times the gross amount needed in Europe to achieve net-zero emissions by 2050; and about 90 percent of all current European social expenditure, or €500 monthly universal income for each European citizen.
Unless tackled, this crisis will handicap Europe on many dimensions, including growth, inclusion, and sustainability, and its strategic autonomy and voice in the world.
Europe can continue to build on its strengths. Its socioeconomic model has served well thus far. But if companies are to play at the scale and speed needed to compete in a world in which technology disruption is spreading everywhere, often with winner-takes-most dynamics, a reevaluation of long-held beliefs and trade-offs may be needed. An integrated package of initiatives could create an environment that enables them to do so—in the process helping to ensure that today’s high quality of life for many of Europe’s citizens is preserved for the long term.
Europe has historically had a strong record on sustainability and inclusion, with a mixed picture on growth
Continuing to better the lives of all Europeans over the long haul requires sustainability, inclusion, and growth. The three reinforce—or can undermine—one another; it is not a question of or, but and.
Where does Europe stand? (See sidebar, “Europe: Geographic scope of research”).
Europe is a leader on sustainability and inclusion, at least in Northern and continental Europe, our analysis shows (Exhibit 1). When Europe works, it works well. However, the region’s performance on growth is less strong. As in the United States, per capita GDP growth was sluggish over the past two decades. The per capita GDP of Europe today is 30 percent below that of the United States. That gap had been narrowing but is no longer doing so.
Exhibit 1
We strive to provide individuals with disabilities equal access to our website. If you would like information about this content we will be happy to work with you. Please email us at: McKinsey_Website_Accessibility@mckinsey.com
On sustainability, Europe has 2.4 times lower CO2 emissions per capita than the United States, and 1.8 times lower CO2 emissions per unit of GDP.
Both emissions per capita and emissions per unit of GDP have decreased faster in Europe than in the United States since 1990. Europe has also pledged to achieve net zero carbon emissions before other regions.
On inclusion, Europe leads on most dimensions, including equality, social progress, and life satisfaction. Income inequality as measured by the Gini index is only 30.
It is 41 in the United States. On social mobility, all top ten countries in the Social Mobility Index published by the World Economic Forum are European.
Europe overall has the highest life expectancy in the world: the EU-27 average is 80 years (80.3 for the EU-30); it is 79 in the United States and 77 in China.
On growth and prosperity, Europe tracked other advanced economies’ sluggish growth of per capita GDP at a compound annual rate of 1.2 percent, similar to 1.1 percent in the United States, between 2000 and 2019. However, the United States has been growing in total GDP terms at 1.9 percent a year, compared with Europe at 1.4 percent annually, reflecting higher population growth. Europe’s per capita GDP is still some 30 percent lower than that of the United States. Forty percent of this gap is due to consciously different labor choices (for instance, earlier retirement ages and more vacation and parental leave). An additional 30 percent is driven by persistently large divides between different regions of Europe. Still, along the income distribution, earnings are higher in the United States for the first nine deciles, while only the bottom 10 percent of Europeans have higher income than those in the United States.
Corporate Europe is falling behind as tech weakness permeates sectors
Corporate Europe’s long-standing weakness in tech is ever more evident in today’s figures. This gap has long been considered a result of specialization and competitive advantage elsewhere—that Europe is strong in other sectors such as chemicals, materials, and fashion, for instance—meaning that the weakness is therefore not something to worry about. However, this is no longer true. Technology is now permeating all sectors via transversal technologies such as artificial intelligence (AI), the Bio Revolution, and the cloud.
Technology is now permeating all sectors via transversal technologies such as artificial intelligence, the Bio Revolution, and the cloud.
Europe’s clear and well-known weakness in tech is the source of a large and growing corporate performance challenge
Data show that Europe’s corporate performance is underwhelming in aggregate. To understand differences in corporate performance, we used McKinsey’s Corporate Performance and Analytics Tool (CPAT) to examine a sample of more than 12,000 companies around the world with revenue of more than $1 billion.
Between 2014 and 2019, large European companies were 20 percent less profitable (measured by return on invested capital, or ROIC), grew revenues 40 percent more slowly, invested 8 percent less (capital expenditure relative to the stock of invested capital), and spent 40 percent less on R&D than other companies in the sample.
Most of the differences are observable in technology-creating industries, specifically ICT and pharmaceuticals.
Together, these sectors account for 90 percent of the ROIC gap, 80 percent of the investment gap, 60 percent of the growth gap, and 75 percent of the R&D gap (Exhibit 2).
Exhibit 2
We strive to provide individuals with disabilities equal access to our website. If you would like information about this content we will be happy to work with you. Please email us at: McKinsey_Website_Accessibility@mckinsey.com
As technology permeates all sectors and corporate scale advantages and winner-take-most dynamics increase, Europe’s current approach is no longer tenable
ICT used to be a sector; now it is everywhere. The technology base built in ICT has spawned a range of transversal technologies that are spreading horizontally across most vertical sectors. Value creation is shifting to these horizontal areas, with winner-take-most dynamics and network effects in technology creation and scale advantages in technology adoption. The World Economic Forum estimates that 70 percent of the new value created in the whole economy over the next ten years will be digitally enabled, a momentum further accelerated by the COVID-19 pandemic (Exhibit 3).
Exhibit 3
We strive to provide individuals with disabilities equal access to our website. If you would like information about this content we will be happy to work with you. Please email us at: McKinsey_Website_Accessibility@mckinsey.com
Europe’s lack of scale in transversal technologies jeopardizes its position in nearly all sectors, including current strongholds like automotive and luxury goods
The fact that Europe did not keep pace with the United States in the first technology wave centered on the internet and software now means that Europe is in a weakened position in transversal technologies across sectors. Our analysis looks at ten such transversal technologies on which Europe’s future performance and prosperity hinge. Europe leads on only two of the ten (Exhibit 4).
Exhibit 4
We strive to provide individuals with disabilities equal access to our website. If you would like information about this content we will be happy to work with you. Please email us at: McKinsey_Website_Accessibility@mckinsey.com
To give just a few examples, in quantum computing, 50 percent of the top ten major tech companies investing in this transversal technology are in the United States, 40 percent in China, and none in in the EU. In 5G, a key element of the future of connectivity, China captures nearly 60 percent of external funding, with the United States at 27 percent and Europe at 11 percent. In AI, the United States captured 40 percent of external funding in 2015–20. Europe captured 12 percent and Asia (including China) 32 percent. In biotech, Europe has a strong science base and a robust pool of talent, and it proved during the pandemic that it can innovate. However, investment in biotech varies among regions. In 2018–20, the United States spent $260 billion, Europe $42 billion, and China $19 billion.
The fact that Europe did not keep pace with the United States in the first technology wave centered on the internet and software now means that Europe is in a weakened position in transversal technologies across sectors.
In cleantech, Europe is more ambitious than most other regions on targets for the reduction of carbon emissions by 2030 but is losing ground in the next wave of cleantech. European players hold 38 percent more cleantech patents than firms in the United States, and more than double the number in China, and have more installed mature technologies per capita. Overall, however, Europe’s prospects of leading on cleantech are fading. China leads on cleantech production in nearly all areas, often with market shares of more than 50 percent, and the United States leads on most breakthrough technologies.
Europe’s lack of scale in transversal technologies jeopardizes its position in nearly all sectors, including current strongholds like automotive and luxury goods. In automotive, US manufacturers account for close to 70 percent of all kilometers made by level 4 fully autonomous vehicles.
The value at stake is high, not only for growth but also for sustainability, inclusion, and Europe’s strategic autonomy
At stake are not only the performance of Europe’s companies, its tech prowess, and its economic growth and prosperity, but also its progress thus far on sustainability and inclusion. Although there are debates over whether lower growth is needed to achieve sustainability and arrest climate change, the opposite argument is compelling: growth strengthens confidence and creates a healthy investment climate to generate sustainability-related innovation and new income streams that are needed to pay for the energy transition. Lagging growth could, moreover, undermine inclusion by limiting the pool of funds available to spend on social programs.
If Europe is not able to improve on transversal technologies, European firms could miss out on a value-added opportunity of €2 trillion to €4 trillion a year by 2040—value that could translate into higher wages, better healthcare, more sustainability investments, and so on. The value at stake equates to 30 to 70 percent of Europe’s forecast GDP growth in GDP between 2019 and 2040, or one percentage point of growth a year.
For further context, this would be equivalent to six times the amount needed to transition to net-zero emissions.
And it would amount to about 90 percent of all current social expenditure in Europe (Exhibit 5).
Exhibit 5
We strive to provide individuals with disabilities equal access to our website. If you would like information about this content we will be happy to work with you. Please email us at: McKinsey_Website_Accessibility@mckinsey.com
There has been much discussion about energy dependence and autonomy, but global economic shifts accentuate the need for strategic autonomy on critical technologies. Technological autonomy is compatible with open economies and global collaboration. It can be achieved via multiple independent global sourcing options as well as a strong footprint of globally leading firms in Europe. But it will also require capability buildup by, and scaling of, European firms. Today, for instance, semiconductors produced in Europe meet just 9 percent of European demand, and European companies have only about 10 percent of the market across the semiconductor value chain. And Europe has no market player with a market share in infrastructure-as-a-service of more than 1 percent.
Much discussion has been taking place about energy dependence and autonomy, but geopolitical shifts also accentuate the need for strategic autonomy on critical technologies.
European decision makers and companies need to go on the offensive for a step change on technological capabilities and competitiveness
Europe can, and should, continue to leverage its many strengths. They include its high-quality education systems, which produce leading science, technology, engineering, and math (STEM) talent as well as some of the most productive vocationally educated workers.
Europe is also the most open and connected large economy in the world.
However, the stakes are so high for Europe that decision makers may want to consider breaking new ground and reevaluating trade-offs in a way that has been uncomfortable heretofore.
As winner-takes-most dynamics spread, Europe needs to play at greater scale and speed and to level the playing field for its firms to compete
As the sources of competition—and growth—shift toward disruptive innovation and intangibles, a winner-takes-most dynamic emerges in which scale, speed, and established tech ecosystems are increasingly vital. A changing geopolitical landscape complicates and deepens that challenge.
In this context, a range of challenges put Europe at a disadvantage. Among them, four stand out and mutually reinforce one another: fragmentation and lack of scale; lack of established technology ecosystems; less developed risk-capital funding; and a regulatory environment that could be more supportive of disruption and innovation.
These challenges are well known among Europe’s leaders, who keenly appreciate what needs to be done at the institutional level. Many initiatives are being designed and launched. In the EU, the €95 billion Horizon Europe program, the Smart Specialization initiative, the Important Projects of Common European Interest framework, and the Digital Decade program are but a few recent examples.
Yet if Europe wants to address its corporate performance gap and avoid a slow-motion crisis unfolding over the years ahead, it could usefully consider one question: does the sum total of all the initiatives under way and planned not only match the scale of what leading regions are doing but exceed it, and therefore enable catch-up from today’s weaker position?
To help European firms to compete, Europe could reevaluate trade-offs on 11 policy and regulatory initiatives
As a thought starter, we offer 11 initiatives that could form part of an integrated package to change the rules of the game for European firms and overcome a range of handicaps (Exhibit 6). They would enable firms to build scale and attract scale-up funding, operate at higher speed and with greater degrees of freedom, and level the playing field with other regions and established firms. Many have been topics of long-running debates and come with major trade-offs, yet this diagnostic suggests revisiting the current stance on them. The initial response to the invasion of Ukraine shows that Europe can leverage its scale and move rapidly when faced with a severe challenge. A similar approach will also be needed to address its slow-motion technology and competitiveness crisis. We invite comments and collaboration to progress these initial ideas.
Exhibit 6
We strive to provide individuals with disabilities equal access to our website. If you would like information about this content we will be happy to work with you. Please email us at: McKinsey_Website_Accessibility@mckinsey.com
Scale and scale-up funding. In transversal technologies where scale of markets, firms, and investment matters, could Europe increase and pool its resources, develop a European corporate rule book for high-growth firms, and facilitate and encourage cross-border consolidation, including by completing the Single Market? Could Europe amplify the pool of scale-up capital and consider pooling more public procurement and R&D support among a coalition of the willing? Europe might consider increasing development support to Central, Eastern, and parts of Southern Europe.
Speed and simplicity. In certain breakthrough technologies, could Europe rebalance its regulatory approach from a precautionary consumer-protection imperative to one that balances costs and benefits of rapid experimentation and disruptive innovation? Could Europe consider developing fast-track regulatory approval and decision-making processes, particularly in the case of disruptive innovation? And what scope is there to embrace faster labor reallocation and reskilling in the face of spreading disruption?
Level playing field. Where might state intervention support the competitiveness of European firms in a global context? Could Europe consider ensuring a level playing field for smaller firms around natural digital monopolies? Could Europe initiate a debate about how to protect nascent technology-savvy firms before they face the full force of global-scale competitors? Finally, could Europe consider ways of becoming a stronger magnet for talent?
Whether the competitive arena improves or not, corporate leaders and owners need to step up their game to take risks and compete
Even if policy and regulation create a more enabling environment in which European firms can compete, they, too, need to step up, developing scale and agility in order to grow and succeed not only on the national and regional levels, but globally. Options to consider include the following:
Set stretch long-term targets and adjust incentives. In the current environment of disruptions, corporations need to aim beyond their incumbent business, develop a vision for global leadership ten to 20 years out, and take risks and deploy capital and R&D investment commensurate with that vision. European companies and their boards could also consider adjusting executive and employee compensation to better align with those visions and the risk-taking needed. Today, only about 5 percent of the private-sector workforce in Europe has some kind of employee ownership, compared with about 20 percent in the United States.
The largest European tech companies have already taken this approach.
Leverage programmatic M&A and alliances to acquire the scale and capabilities needed. This would include cross-border European and global consolidation, including—painfully—sell-side M&A where global leadership is out of reach. It would also include using vertical and capability-based acquisitions to ramp up the development of innovation strengths and ecosystems, for instance using corporate venture capital. Companies should also be proactive in seeking and developing cross-sector alliances to accelerate the development of transversal technologies. Companies and entrepreneurs can also seek to set up new disruptors.
Invest in innovation and technology governance and capabilities at scale and pace. Companies will need to implement agile and more customer-centric innovation governance able to deal with higher-risk, long-term projects. They will need to find or reallocate funds for long-term innovation and business development at a larger scale than they used to. And they will need to build skills.
European countries have been leaders on sustainability and inclusion. They are now concerned with the security of supply chains, energy, food, and defense. How much should the region also worry about its corporate and technology gap, which is jeopardizing future growth and strategic autonomy—and when? Can the momentum of common action triggered by war in Ukraine now also provide the impetus to make the trade-offs needed for technology and competitiveness that have long felt difficult?
More work will likely be needed to determine how to tackle Europe’s gaps in corporate performance and innovation in detail and in practice, technology by technology and sector by sector, building resilience into the European model for the long term. This article marks the start of a McKinsey initiative to gather insights across Europe in an effort to make a contribution to addressing these questions.