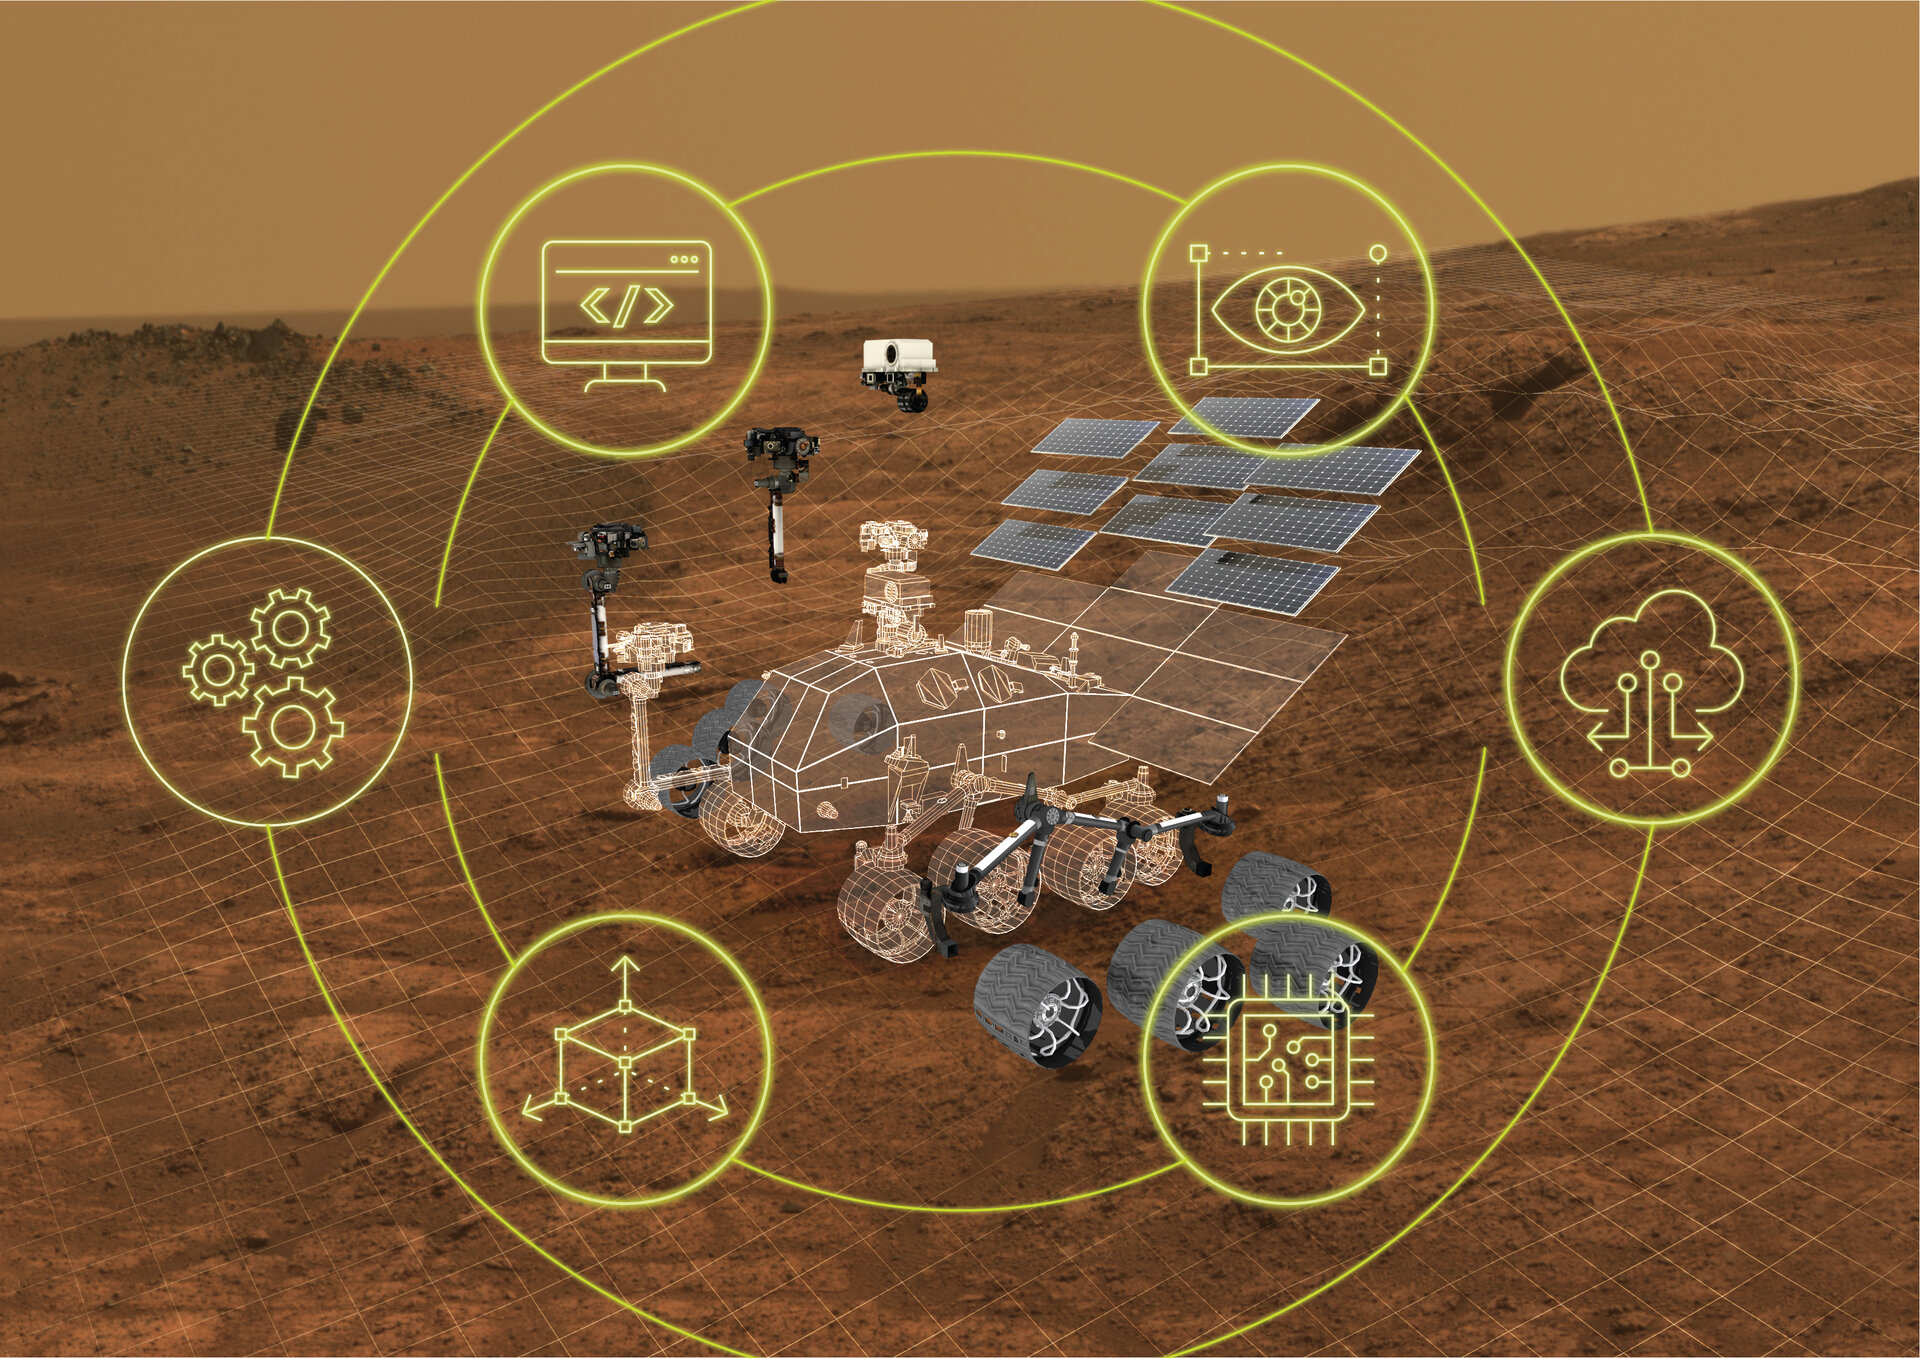
ESA Director Typical Josef Aschbacher’s Agenda 2025 has established the future training course of Europe in area, constructing on the Agency’s Engineering Strategy which specifics how our continent is building the critical engineering to get it wherever it is going. Reflecting four many years of development due to the fact it was very first unveiled and the new guidance from Agenda 2025, ESA has now updated the Know-how Method appropriately. It has been released in time for the Agency’s Council at Ministerial Degree in Paris on 22 – 23 November, demonstrating the elementary position of technological innovation across all ESA missions and programmes.
ESA Director Standard Josef Aschbacher
Engineering – the software of scientific understanding for simple functions – could sound summary, but our ability to invent and evolve and master technological know-how and equipment is basic to humanity as a species, driving us from the East African savannah to every single corner of earth Earth, and beyond.
Director Common Josef Aschbacher states: “Technology is at the heart of every thing ESA does. On the eve of ESA’s Council at Ministerial Degree, it is crystal clear that strengthening Europe’s backlinks past planet Earth – to secure our accessibility to room, fortify our aggressive position and proceed to draw reward from it – simply cannot be finished without the need of far better, a lot quicker and much more clear know-how growth. The ESA Technological know-how Strategy is obvious and bold and will be an enabler for long run ESA missions, making sure Europe’s position as a fierce world wide competitor.”
Flexible photo voltaic arrays for foreseeable future house missions
Responding to Agenda 2025
On 1st turning into Director Common, Josef Aschbacher introduced Agenda 2025 – his eyesight of a stronger foreseeable future European place sector. It begins with a point out of the Agency’s Know-how Method, originally issued in 2018, which addresses how ESA develops technologies essential to achieve Europe’s goals in space, and returns to the topic regularly.
ESA Director of Know-how, Engineering and High quality Torben Henriksen clarifies: “Underlining the great importance of ESA’s technical competence, Agenda 2025 questioned for a emphasis on velocity in the introduction of new systems, a doubling of investment decision on ‘game-changing’ systems and the launching of three new technological innovation R&D initiatives.
“This new Version 1.2 of the Technological know-how Technique incorporates the technology steerage from Agenda 2025, displaying how Agenda 2025 will be executed in apply throughout all ESA’s R&D programmes, as effectively as how significantly the Agency has progressed throughout the previous four many years.”
ESA’s Technologies CubeSats
Development in technologies targets
Of the four targets established out in the authentic edition of the Know-how Tactic, the Director Typical gave priority to this one: 30{4224f0a76978c4d6828175c7edfc499fc862aa95a2f708cd5006c57745b2aaca} more quickly progress and adoption of ground breaking technological innovation. In practice this has intended novel procedures, approaches and systems, enabling Europe to choose quicker advantage from the introduction of new systems.
This consists of a tripling of the selection of In-Orbit Demonstration missions from 2020 – 2024 in comparison to 2015 – 2019, allowing early testing of promising systems in place, specifically using miniature ‘CubeSats’. In addition the time desired to advance technologies selected for In-Orbit Demonstration from Technology Readiness Levels 4/5 to TRL 7/8 are slashed by 50 percent, indicating they get to area faster.
Testing COTS pieces for place missions
The greater use of ‘commercial off the shelf’ sections, essential to get innovation into room more rapidly, has been facilitated by way of a focused COTS technique and connected mission classification risk product. COTS elements tend to be more highly developed and economical as opposed to their space-grade equivalents. Adopting them permits place missions to benefit from rapid evolving terrestrial technology previously, though does have to have a careful consideration of the hazard as opposed to benefit level.
Improved overall flexibility, modularity and scalability are also getting sought through a top-down technique (unit systems to modules), and standardization of interfaces and Integration Testing methodology for quicker adoption, these kinds of as for the Sophisticated Knowledge Managing Architecture (ADHA), and the State-of-the-art Electrical power Architecture (APA).
Integrated circuits for room on wafers
A 2nd goal is to develop critical technologies allowing Europe to achieve a a person order of magnitude improvement in price performance with each new era of area units, which encompasses ESA’s entire selection of pursuits: from getting an purchase of magnitude more scientific benefit out of upcoming era science missions to lessening the charge for every useful bit transmitted by telecom satellite units by one particular get of magnitude. To support obtain this, Agenda 2025 has led to a precise emphasis on added technologies – see the specific new initiatives shown beneath.
Attention is currently being primarily compensated to large information analytics systems, close-to-stop program design optimisation and on-board intelligence for smart processing to raise the worth for every pixel, miniaturisation of instrument technologies and payloads as well as technologies progress in the domain of optics and sensors.
Design-primarily based technique engineering
The third concentrate on is to reach a 30{4224f0a76978c4d6828175c7edfc499fc862aa95a2f708cd5006c57745b2aaca} advancement in spacecraft advancement time, aiming to fully digitalise the workflow from Stage B2 notion improvement via to producing, integration and testing employing Product-Dependent Process Engineering (MBSE), that means that classic documentation is replaced with shared digital versions. Considerable attempts throughout the very last two years have allowed ESA to use MBSE as part of the baseline for new Stage A scientific tests. Several ESA missions have acted as MBSE forerunners, together with Euclid, Plato and Galileo 2nd Technology.
Enhanced versatility and scalability are also being sought through the greatest adoption of modular room method types and standardisation, these as the Superior Knowledge Managing Architecture technique, as nicely as maximising the speed of introducing new terrestrial technological progress to spacecraft. ESA’s Electronic Layout-2-Produce and Advanced Manufacturing R&D initiatives are also relevant right here.
The fourth focus on is to invert Europe’s contribution to house particles by 2030, showing our ambition to go away the valuable room environments in a cleanse state for the future. Addressing this contains proposing a formal ‘zero debris’ solution for all long run ESA missions, which include mechanical interfaces for capture as now performed for Copernicus Growth missions to be organized for removing by an external servicer as very well as demonstrating these types of a elimination by 2025 by means of the ClearSpace-1 ADRIOS mission, currently in planning.
ClearSpace-1 ADRIOS for orbital debris removing
In the meantime ESA’s cleansat initiative is producing a large assortment of technological innovation to guarantee that ESA satellites can reliably arrive at the close of their mission lifetimes with out producing particles, ordinarily by way of deorbiting or reorbiting out of really trafficked orbits, in conjunction with ESA and worldwide particles restrictions.
Trio of new engineering themes
The Director General’s instruction to concentrate on the more rapidly advancement and implementation of revolutionary technologies has also led to the creation of a few model new engineering themes, signing up for the existing initiatives on COTS and Electrical, Electronic and Electro-mechanical (EEE) parts Superior Manufacturing Digitial Style and design 2 Generate Thoroughly clean House and Cyber-security:
Quantum systems – harnessing specific homes of issue that manifest at the pretty tiniest of scales these provide new options in room-centered communications safeguarded by actual physical attributes rather of encryption, the generation of hugely delicate sensors for mapping gravity, tracking Earth features and elementary physics phenomena and ultimately the hugely specific measurement of time.
Advanced propulsion – spanning from air-respiration rocket engines to electric propulsion serving really lower orbits to emerging environmentally friendly propellants, the emphasis is on new propulsion systems for new purposes, to aid new programs and marketplaces though boosting the competitiveness of European propulsion and flight automobile solutions.
In-orbit servicing and building – The ClearSpace-1 ADRIOS mission will exhibit a exclusive company to display the initial removing of a debris product from orbit. To improve Europe’s ability to act sustainably in place, and prepare for an emerging professional market, Europe will exhibit in-area servicing, manufacturing, building and recycling abilities, unlocking new purposes in the approach.
ESA Director of Earth Observation Simonetta Cheli
Simonetta Cheli, ESA Director of Earth Observation adds: “As with all other Directorates, we do the job hand-in-hand with the Directorate of Know-how, Engineering and Top quality and with business for know-how developments, concentrating on a consumer-driven technique to prioritise innovative know-how developments and aid a faster adoption of these systems and methodologies in our ESA missions. Technological synergies generally open up the doors to other markets further than ESA and foster the competitiveness of the European space market.”
ESA Technological innovation System Version 1.2
Torben Henriksen describes: “The Technologies Strategy delivers us with a sound, and formidable tutorial for all our know-how growth programmes, to develop the most suitable engineering, on time and in accordance to the appropriate specs. We have engaged with the distinct buyers on their requires and combined with most up-to-date specialized development have identified structured priority know-how themes. Results in these themes will be vital to reaching the ESA Technologies Strategy’s major targets.
“Reflecting the maturing, ever more numerous and modern European house sector, we have also created it less difficult than at any time for anyone, in particular new providers coming into the house sector, to propose new concepts for place technology R&D via ESA Discovery’s open up-access Open Room Innovation Platform. Implementing the approach will enable Europe to achieve our ambitions in space, in certain the aims outlined in Agenda 2025.”
Study ESA’s current Edition 1.2 of the Engineering Technique in comprehensive listed here.
Thank you for liking
You have now preferred this webpage, you can only like it as soon as!
Europe as it is today has been forged in times of crisis. The European Union (EU) was created in response to the ravages of World War II. The fall of the Berlin Wall marked the start of a period of economic catching up by economies in Central and Eastern Europe. The 2008 financial crisis and the eurozone crisis that followed led to more financial cooperation among European countries. The COVID-19 pandemic then triggered a higher level of fiscal coordination through the NextGeneration EU fund.
Most recently, the Russian invasion of Ukraine not only is a humanitarian catastrophe but has exposed a range of fragilities, from food security and energy to defense. The war has accentuated the reality that resilience depends on a strong economy with strategic autonomy in these critical areas that has long been taken for granted.
Technology is pivotal, too. Unless Europe catches up with other major regions on key technologies, it will be vulnerable across all sectors on growth and competitiveness—compromising the region’s relatively robust record on sustainability and inclusion—as well as security and strategic strength, hindering long-term resilience. Given seismic events within its own continent, a robust Europe is arguably needed more than ever. Yet to make that a reality will require the region to address a slow-motion competitiveness crisis that has quietly been unfolding for two decades, centered on its corporate and technology gap with other major regions. That is the topic of this article. Confronting this gap will require leaders to show the same resolve and collaboration as they initially displayed in their response to the war in Ukraine.
Although Europe has many high-performing companies, in aggregate European companies underperform relative to those in other major regions: they are growing more slowly, creating lower returns, and investing less in R&D than their US counterparts. This largely reflects the fact that Europe missed the boat on the last technology revolution, lagging behind on value and growth in information and communications technology (ICT) and on other disruptive innovations.
ICT and other tech sectors have spawned a range of transversal technologies, which are spreading horizontally across sectors and determining competitive dynamics. This research looks at ten transversal technologies and finds that Europe leads on only two of the ten. If Europe is not successful in competing in these technologies, it could also lose its strongholds in traditional industries. To give just one example, Europe has been a leader in automotive but could become a laggard in autonomous driving.
The stakes are high. We estimate that corporate value added of €2 trillion to €4 trillion a year could be at stake by 2040—value that could generate wages, employment, investment, and economic growth to the broader benefit of society. To put the estimated value at stake into perspective, that would be equivalent to 30 to 70 percent of Europe’s forecast GDP growth between 2019 and 2040, or one percentage point of growth a year; six times the gross amount needed in Europe to achieve net-zero emissions by 2050; and about 90 percent of all current European social expenditure, or €500 monthly universal income for each European citizen.
Unless tackled, this crisis will handicap Europe on many dimensions, including growth, inclusion, and sustainability, and its strategic autonomy and voice in the world.
Europe can continue to build on its strengths. Its socioeconomic model has served well thus far. But if companies are to play at the scale and speed needed to compete in a world in which technology disruption is spreading everywhere, often with winner-takes-most dynamics, a reevaluation of long-held beliefs and trade-offs may be needed. An integrated package of initiatives could create an environment that enables them to do so—in the process helping to ensure that today’s high quality of life for many of Europe’s citizens is preserved for the long term.
Europe has historically had a strong record on sustainability and inclusion, with a mixed picture on growth
Continuing to better the lives of all Europeans over the long haul requires sustainability, inclusion, and growth. The three reinforce—or can undermine—one another; it is not a question of or, but and.
Where does Europe stand? (See sidebar, “Europe: Geographic scope of research”).
Europe is a leader on sustainability and inclusion, at least in Northern and continental Europe, our analysis shows (Exhibit 1). When Europe works, it works well. However, the region’s performance on growth is less strong. As in the United States, per capita GDP growth was sluggish over the past two decades. The per capita GDP of Europe today is 30 percent below that of the United States. That gap had been narrowing but is no longer doing so.
Exhibit 1
We strive to provide individuals with disabilities equal access to our website. If you would like information about this content we will be happy to work with you. Please email us at: McKinsey_Website_Accessibility@mckinsey.com
On sustainability, Europe has 2.4 times lower CO2 emissions per capita than the United States, and 1.8 times lower CO2 emissions per unit of GDP.
Both emissions per capita and emissions per unit of GDP have decreased faster in Europe than in the United States since 1990. Europe has also pledged to achieve net zero carbon emissions before other regions.
On inclusion, Europe leads on most dimensions, including equality, social progress, and life satisfaction. Income inequality as measured by the Gini index is only 30.
It is 41 in the United States. On social mobility, all top ten countries in the Social Mobility Index published by the World Economic Forum are European.
Europe overall has the highest life expectancy in the world: the EU-27 average is 80 years (80.3 for the EU-30); it is 79 in the United States and 77 in China.
On growth and prosperity, Europe tracked other advanced economies’ sluggish growth of per capita GDP at a compound annual rate of 1.2 percent, similar to 1.1 percent in the United States, between 2000 and 2019. However, the United States has been growing in total GDP terms at 1.9 percent a year, compared with Europe at 1.4 percent annually, reflecting higher population growth. Europe’s per capita GDP is still some 30 percent lower than that of the United States. Forty percent of this gap is due to consciously different labor choices (for instance, earlier retirement ages and more vacation and parental leave). An additional 30 percent is driven by persistently large divides between different regions of Europe. Still, along the income distribution, earnings are higher in the United States for the first nine deciles, while only the bottom 10 percent of Europeans have higher income than those in the United States.
Corporate Europe is falling behind as tech weakness permeates sectors
Corporate Europe’s long-standing weakness in tech is ever more evident in today’s figures. This gap has long been considered a result of specialization and competitive advantage elsewhere—that Europe is strong in other sectors such as chemicals, materials, and fashion, for instance—meaning that the weakness is therefore not something to worry about. However, this is no longer true. Technology is now permeating all sectors via transversal technologies such as artificial intelligence (AI), the Bio Revolution, and the cloud.
Technology is now permeating all sectors via transversal technologies such as artificial intelligence, the Bio Revolution, and the cloud.
Europe’s clear and well-known weakness in tech is the source of a large and growing corporate performance challenge
Data show that Europe’s corporate performance is underwhelming in aggregate. To understand differences in corporate performance, we used McKinsey’s Corporate Performance and Analytics Tool (CPAT) to examine a sample of more than 12,000 companies around the world with revenue of more than $1 billion.
Between 2014 and 2019, large European companies were 20 percent less profitable (measured by return on invested capital, or ROIC), grew revenues 40 percent more slowly, invested 8 percent less (capital expenditure relative to the stock of invested capital), and spent 40 percent less on R&D than other companies in the sample.
Most of the differences are observable in technology-creating industries, specifically ICT and pharmaceuticals.
Together, these sectors account for 90 percent of the ROIC gap, 80 percent of the investment gap, 60 percent of the growth gap, and 75 percent of the R&D gap (Exhibit 2).
Exhibit 2
We strive to provide individuals with disabilities equal access to our website. If you would like information about this content we will be happy to work with you. Please email us at: McKinsey_Website_Accessibility@mckinsey.com
As technology permeates all sectors and corporate scale advantages and winner-take-most dynamics increase, Europe’s current approach is no longer tenable
ICT used to be a sector; now it is everywhere. The technology base built in ICT has spawned a range of transversal technologies that are spreading horizontally across most vertical sectors. Value creation is shifting to these horizontal areas, with winner-take-most dynamics and network effects in technology creation and scale advantages in technology adoption. The World Economic Forum estimates that 70 percent of the new value created in the whole economy over the next ten years will be digitally enabled, a momentum further accelerated by the COVID-19 pandemic (Exhibit 3).
Exhibit 3
We strive to provide individuals with disabilities equal access to our website. If you would like information about this content we will be happy to work with you. Please email us at: McKinsey_Website_Accessibility@mckinsey.com
Europe’s lack of scale in transversal technologies jeopardizes its position in nearly all sectors, including current strongholds like automotive and luxury goods
The fact that Europe did not keep pace with the United States in the first technology wave centered on the internet and software now means that Europe is in a weakened position in transversal technologies across sectors. Our analysis looks at ten such transversal technologies on which Europe’s future performance and prosperity hinge. Europe leads on only two of the ten (Exhibit 4).
Exhibit 4
We strive to provide individuals with disabilities equal access to our website. If you would like information about this content we will be happy to work with you. Please email us at: McKinsey_Website_Accessibility@mckinsey.com
To give just a few examples, in quantum computing, 50 percent of the top ten major tech companies investing in this transversal technology are in the United States, 40 percent in China, and none in in the EU. In 5G, a key element of the future of connectivity, China captures nearly 60 percent of external funding, with the United States at 27 percent and Europe at 11 percent. In AI, the United States captured 40 percent of external funding in 2015–20. Europe captured 12 percent and Asia (including China) 32 percent. In biotech, Europe has a strong science base and a robust pool of talent, and it proved during the pandemic that it can innovate. However, investment in biotech varies among regions. In 2018–20, the United States spent $260 billion, Europe $42 billion, and China $19 billion.
The fact that Europe did not keep pace with the United States in the first technology wave centered on the internet and software now means that Europe is in a weakened position in transversal technologies across sectors.
In cleantech, Europe is more ambitious than most other regions on targets for the reduction of carbon emissions by 2030 but is losing ground in the next wave of cleantech. European players hold 38 percent more cleantech patents than firms in the United States, and more than double the number in China, and have more installed mature technologies per capita. Overall, however, Europe’s prospects of leading on cleantech are fading. China leads on cleantech production in nearly all areas, often with market shares of more than 50 percent, and the United States leads on most breakthrough technologies.
Europe’s lack of scale in transversal technologies jeopardizes its position in nearly all sectors, including current strongholds like automotive and luxury goods. In automotive, US manufacturers account for close to 70 percent of all kilometers made by level 4 fully autonomous vehicles.
The value at stake is high, not only for growth but also for sustainability, inclusion, and Europe’s strategic autonomy
At stake are not only the performance of Europe’s companies, its tech prowess, and its economic growth and prosperity, but also its progress thus far on sustainability and inclusion. Although there are debates over whether lower growth is needed to achieve sustainability and arrest climate change, the opposite argument is compelling: growth strengthens confidence and creates a healthy investment climate to generate sustainability-related innovation and new income streams that are needed to pay for the energy transition. Lagging growth could, moreover, undermine inclusion by limiting the pool of funds available to spend on social programs.
If Europe is not able to improve on transversal technologies, European firms could miss out on a value-added opportunity of €2 trillion to €4 trillion a year by 2040—value that could translate into higher wages, better healthcare, more sustainability investments, and so on. The value at stake equates to 30 to 70 percent of Europe’s forecast GDP growth in GDP between 2019 and 2040, or one percentage point of growth a year.
For further context, this would be equivalent to six times the amount needed to transition to net-zero emissions.
And it would amount to about 90 percent of all current social expenditure in Europe (Exhibit 5).
Exhibit 5
We strive to provide individuals with disabilities equal access to our website. If you would like information about this content we will be happy to work with you. Please email us at: McKinsey_Website_Accessibility@mckinsey.com
There has been much discussion about energy dependence and autonomy, but global economic shifts accentuate the need for strategic autonomy on critical technologies. Technological autonomy is compatible with open economies and global collaboration. It can be achieved via multiple independent global sourcing options as well as a strong footprint of globally leading firms in Europe. But it will also require capability buildup by, and scaling of, European firms. Today, for instance, semiconductors produced in Europe meet just 9 percent of European demand, and European companies have only about 10 percent of the market across the semiconductor value chain. And Europe has no market player with a market share in infrastructure-as-a-service of more than 1 percent.
Much discussion has been taking place about energy dependence and autonomy, but geopolitical shifts also accentuate the need for strategic autonomy on critical technologies.
European decision makers and companies need to go on the offensive for a step change on technological capabilities and competitiveness
Europe can, and should, continue to leverage its many strengths. They include its high-quality education systems, which produce leading science, technology, engineering, and math (STEM) talent as well as some of the most productive vocationally educated workers.
Europe is also the most open and connected large economy in the world.
However, the stakes are so high for Europe that decision makers may want to consider breaking new ground and reevaluating trade-offs in a way that has been uncomfortable heretofore.
As winner-takes-most dynamics spread, Europe needs to play at greater scale and speed and to level the playing field for its firms to compete
As the sources of competition—and growth—shift toward disruptive innovation and intangibles, a winner-takes-most dynamic emerges in which scale, speed, and established tech ecosystems are increasingly vital. A changing geopolitical landscape complicates and deepens that challenge.
In this context, a range of challenges put Europe at a disadvantage. Among them, four stand out and mutually reinforce one another: fragmentation and lack of scale; lack of established technology ecosystems; less developed risk-capital funding; and a regulatory environment that could be more supportive of disruption and innovation.
These challenges are well known among Europe’s leaders, who keenly appreciate what needs to be done at the institutional level. Many initiatives are being designed and launched. In the EU, the €95 billion Horizon Europe program, the Smart Specialization initiative, the Important Projects of Common European Interest framework, and the Digital Decade program are but a few recent examples.
Yet if Europe wants to address its corporate performance gap and avoid a slow-motion crisis unfolding over the years ahead, it could usefully consider one question: does the sum total of all the initiatives under way and planned not only match the scale of what leading regions are doing but exceed it, and therefore enable catch-up from today’s weaker position?
To help European firms to compete, Europe could reevaluate trade-offs on 11 policy and regulatory initiatives
As a thought starter, we offer 11 initiatives that could form part of an integrated package to change the rules of the game for European firms and overcome a range of handicaps (Exhibit 6). They would enable firms to build scale and attract scale-up funding, operate at higher speed and with greater degrees of freedom, and level the playing field with other regions and established firms. Many have been topics of long-running debates and come with major trade-offs, yet this diagnostic suggests revisiting the current stance on them. The initial response to the invasion of Ukraine shows that Europe can leverage its scale and move rapidly when faced with a severe challenge. A similar approach will also be needed to address its slow-motion technology and competitiveness crisis. We invite comments and collaboration to progress these initial ideas.
Exhibit 6
We strive to provide individuals with disabilities equal access to our website. If you would like information about this content we will be happy to work with you. Please email us at: McKinsey_Website_Accessibility@mckinsey.com
Scale and scale-up funding. In transversal technologies where scale of markets, firms, and investment matters, could Europe increase and pool its resources, develop a European corporate rule book for high-growth firms, and facilitate and encourage cross-border consolidation, including by completing the Single Market? Could Europe amplify the pool of scale-up capital and consider pooling more public procurement and R&D support among a coalition of the willing? Europe might consider increasing development support to Central, Eastern, and parts of Southern Europe.
Speed and simplicity. In certain breakthrough technologies, could Europe rebalance its regulatory approach from a precautionary consumer-protection imperative to one that balances costs and benefits of rapid experimentation and disruptive innovation? Could Europe consider developing fast-track regulatory approval and decision-making processes, particularly in the case of disruptive innovation? And what scope is there to embrace faster labor reallocation and reskilling in the face of spreading disruption?
Level playing field. Where might state intervention support the competitiveness of European firms in a global context? Could Europe consider ensuring a level playing field for smaller firms around natural digital monopolies? Could Europe initiate a debate about how to protect nascent technology-savvy firms before they face the full force of global-scale competitors? Finally, could Europe consider ways of becoming a stronger magnet for talent?
Whether the competitive arena improves or not, corporate leaders and owners need to step up their game to take risks and compete
Even if policy and regulation create a more enabling environment in which European firms can compete, they, too, need to step up, developing scale and agility in order to grow and succeed not only on the national and regional levels, but globally. Options to consider include the following:
Set stretch long-term targets and adjust incentives. In the current environment of disruptions, corporations need to aim beyond their incumbent business, develop a vision for global leadership ten to 20 years out, and take risks and deploy capital and R&D investment commensurate with that vision. European companies and their boards could also consider adjusting executive and employee compensation to better align with those visions and the risk-taking needed. Today, only about 5 percent of the private-sector workforce in Europe has some kind of employee ownership, compared with about 20 percent in the United States.
The largest European tech companies have already taken this approach.
Leverage programmatic M&A and alliances to acquire the scale and capabilities needed. This would include cross-border European and global consolidation, including—painfully—sell-side M&A where global leadership is out of reach. It would also include using vertical and capability-based acquisitions to ramp up the development of innovation strengths and ecosystems, for instance using corporate venture capital. Companies should also be proactive in seeking and developing cross-sector alliances to accelerate the development of transversal technologies. Companies and entrepreneurs can also seek to set up new disruptors.
Invest in innovation and technology governance and capabilities at scale and pace. Companies will need to implement agile and more customer-centric innovation governance able to deal with higher-risk, long-term projects. They will need to find or reallocate funds for long-term innovation and business development at a larger scale than they used to. And they will need to build skills.
European countries have been leaders on sustainability and inclusion. They are now concerned with the security of supply chains, energy, food, and defense. How much should the region also worry about its corporate and technology gap, which is jeopardizing future growth and strategic autonomy—and when? Can the momentum of common action triggered by war in Ukraine now also provide the impetus to make the trade-offs needed for technology and competitiveness that have long felt difficult?
More work will likely be needed to determine how to tackle Europe’s gaps in corporate performance and innovation in detail and in practice, technology by technology and sector by sector, building resilience into the European model for the long term. This article marks the start of a McKinsey initiative to gather insights across Europe in an effort to make a contribution to addressing these questions.